
The Dutch AI-sector giant ASML reported Q3 revenue of EUR 11.66 billion versus EUR 11.72 billion expected, while the company’s shares fell around 4% in the initial reaction, even though net profit clearly beat consensus, reaching EUR 4.96 billion versus the EUR 4.1 billion forecast. However, at demanding valuation levels, even the smallest blemish in sales momentum can weigh on sentiment, and this appears to be exactly what we are seeing. Overall, the company’s report was very strong and also confirmed a significant increase in AI-sector demand from already elevated levels. In this context, revenue missing expectations by a few million euros should hardly be shareholders’ biggest concern — the key question is whether the report points to any other “red flags.” Looking more closely, the answer appears to be clearly no, and we see nothing in the results that poses a “threat” to the continuation of the technology-sector bull market. If anything, the report seems to support the case for improving sentiment across the AI infrastructure segment.
- The company narrowed its full-year revenue guidance to a range of EUR 44–45 billion, raising the lower end from the previous EUR 43 billion. Demand remains very strong, particularly due to AI-related investment, while some customers are already expressing interest in placing orders for 2029–2030.
- ASML believes that currently planned supply for 2027 and 2028 will not be sufficient to fully meet demand, and the company continues to evaluate further capacity expansion.
- For the next quarter, Q4, ASML expects sales of EUR 14.2–15.2 billion, with the upper end of the range exceeding the LSEG consensus of EUR 14.2 billion.
- Additional support for the long-term outlook comes from Samsung and TSMC committing to the use of High NA EUV systems, which are expected to be crucial for the next generation of the most advanced semiconductors.
The quality of ASML’s results was better than the headline revenue figure suggests
ASML’s third-quarter results looked mixed only at first glance. Net sales came in marginally below expectations, but far more important was the scale of the positive surprise on profitability. Net profit reached EUR 4.96 billion versus around EUR 4.11 billion expected, while gross margin stood at 57.5% compared with approximately 56.1% expected. This suggests that ASML is not only delivering very high sales volumes but is also maintaining exceptionally strong unit economics across its business. An important contributor was Installed Base Management sales of EUR 3.3 billion, which exceeded the company’s earlier assumptions. Rising customer spending on upgrades and improvements to the efficiency of already installed systems increases the share of more recurring revenue and partially reduces ASML’s dependence on the delivery cycle for new machines. At the same time, the company sold 113 new lithography systems and 8 used systems, compared with 86 and 5, respectively, in the previous quarter, pointing to a clear acceleration in operating activity. The key takeaway is therefore not the modest revenue miss, but the fact that ASML is generating substantially more profit from every euro of revenue than the market had expected. For a business with such high barriers to entry and such a unique technological position, this means the company’s competitive advantage is increasingly being reflected in margins, rather than merely in nominal revenue growth.
ASML raises its outlook for the third time: the AI boom is already translating into hard numbers
An even stronger element of the report was the outlook. ASML improved its 2026 guidance for the third consecutive quarter, narrowing its expected sales range. At the same time, the company now expects a full-year gross margin of around 56%, compared with its previous range of 54% to 56%. Raising the lower end of guidance, rather than simply lifting the upside scenario, is particularly important. It suggests that management is becoming increasingly confident about both demand realization and profitability toward the end of the year. For Q4, ASML forecasts EUR 14.2–15.2 billion in sales and a gross margin of around 57%. The upper end of the revenue range exceeds previous market expectations, while the projected margin remains exceptionally high for a manufacturer of such complex industrial equipment. The company also expects its EUV business to grow by more than 45% this year, while the non-EUV segment is projected to expand by around 20% year over year. This is particularly important from a valuation perspective. For several quarters, the market has been paying a premium for the expected increase in AI infrastructure investment, but the current report shows that this is no longer purely a story based on future expectations. AI-related demand is increasingly visible in sales, margins and repeatedly upgraded forecasts. In practice, this means the main question for investors is gradually shifting away from whether demand exists at all and toward how long ASML can sustain its current growth rate under existing supply constraints.
ASML’s problem is not a lack of demand, but its ability to meet it
The most strategically important information in the report, however, is the extension of the order horizon far beyond the current investment cycle. Management indicated that some customers are beginning to express interest in equipment deliveries as far out as 2029 and 2030. For an industrial company, this represents an exceptionally long period of demand visibility and illustrates how aggressively the world’s largest semiconductor manufacturers are planning future production capacity. Even more importantly, ASML acknowledged that currently planned production capacity for 2027 and 2028 will not be sufficient to fully meet projected customer demand. The company had already planned to increase production capacity by around 30%, but it is now evaluating the possibility of further expansion. This changes the nature of the investment risk: at least at this stage, the main constraint on growth does not appear to be demand for ASML systems, but rather the company’s and its supply chain’s ability to scale production quickly enough. For shareholders, this represents both an opportunity and a risk. A persistent excess of demand over supply could strengthen pricing power, capacity utilization and margins, particularly for the most advanced EUV systems. On the other hand, further production expansion requires investment, coordination across a highly complex supply chain and the maintenance of extraordinary technological precision. For ASML, the key question over the coming quarters is therefore not so much “will AI continue to generate demand?” but rather how quickly the company can convert its multi-year backlog and customer interest into actual deliveries, revenue and free cash flow.
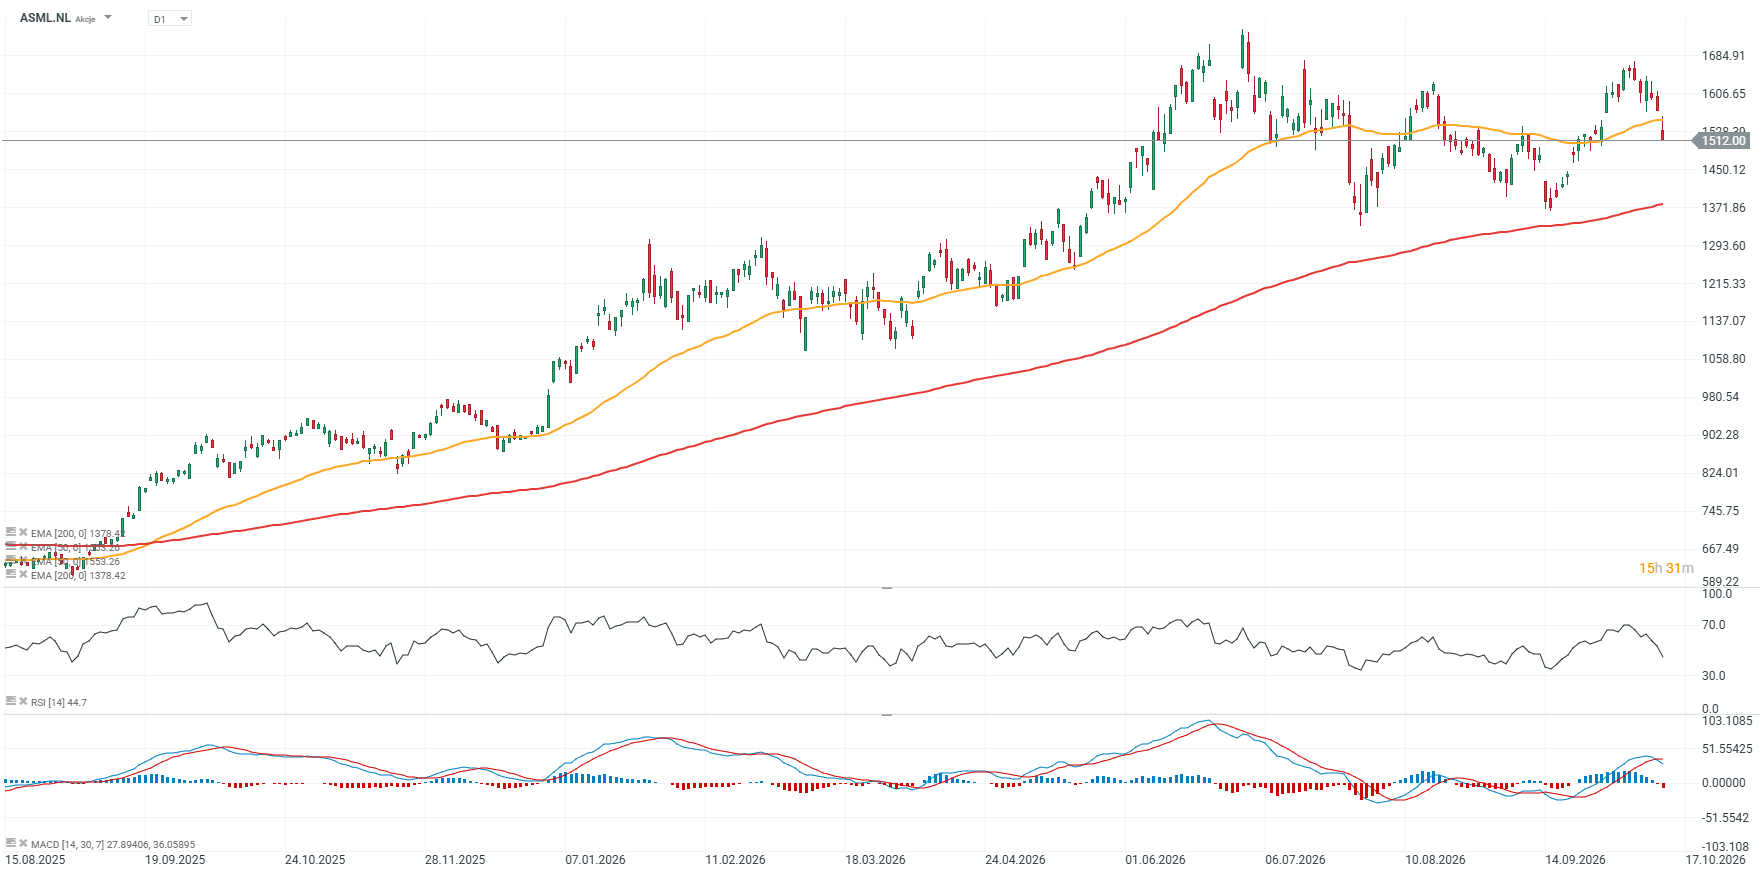
ASML share price chart (D1 interval)
Today, ASML shares are likely to open with a downside gap, although buying activity during the session cannot be ruled out. From a technical perspective, a potentially bearish double-top formation is developing, and if the shares were to fall toward EUR 1,400, where they would also be testing the EMA200 (red line), the risk of a more sustained trend reversal would become considerably more meaningful. For bulls, holding above EUR 1,450, around the September price gap, may prove crucial. The key resistance area currently appears to be around EUR 1,600.
Source: XTB